Saving for a house in Sydney’s competitive property market can feel like climbing a mountain. Many potential homebuyers we meet ask us the same question: “How much do I really need to save for a down payment?”
We understand this challenge, especially for first-time homebuyers looking to secure home loans in Sydney. While the traditional advice suggests a 20% down payment, the reality is more nuanced. As home loans experts in Sydney, we’ve helped countless clients determine their ideal down payment amount based on their unique financial situation.
Understanding Down Payment Basics
While many believe a 20% down payment is mandatory, we’ve helped many first-time homebuyers in Sydney secure home loans with much less. According to recent data, the typical down payment for first-time homebuyers is just 6% of the home’s purchase price.

When considering your down payment amount, here are the key benefits of making a larger contribution:
- Lower monthly payments and reduced interest over time
- Better chances of loan approval with favorable terms
- Potential to avoid Private Mortgage Insurance (PMI)
- Increased initial home equity
- More competitive offer in sellers’ eyes
For example, on a $200,000 home purchase with no down payment and a 30-year fixed-rate loan at 4% interest, you would pay approximately $143,735 in interest over the life of the loan. However, with a 20% down payment ($40,000), you would save over $28,746 in interest payments.
As home loans experts in Sydney, we often explain to our clients that PMI is typically required when putting down less than 20% on conventional loans. This insurance protects the lender and adds to your monthly payments until you reach 20% equity in your home.
The good news is that various loan options exist for different down payment levels. Conventional loans may accept down payments as low as 3%, while FHA loans require just 3.5% down. Your choice will depend on factors like your financial situation, credit score, and long-term homeownership goals.
Smart Strategies for Down Payment Savings
As your trusted home loans experts in Sydney, we’ve helped numerous clients develop effective saving strategies for their down payments. Let’s explore some proven approaches that can accelerate your journey to homeownership.
The foundation of successful down payment saving is automation. We recommend setting up a dedicated high-yield savings account specifically for your down payment funds. By automating regular transfers from your paycheck, you’re essentially paying yourself first and building your savings consistently.
Here are our top-recommended strategies that have helped our Sydney clients:
- Create a separate savings account with competitive interest rates
- Set up automatic paycheck deductions
- Redirect any windfalls (tax returns, bonuses) to savings
- Explore employer assistance programs
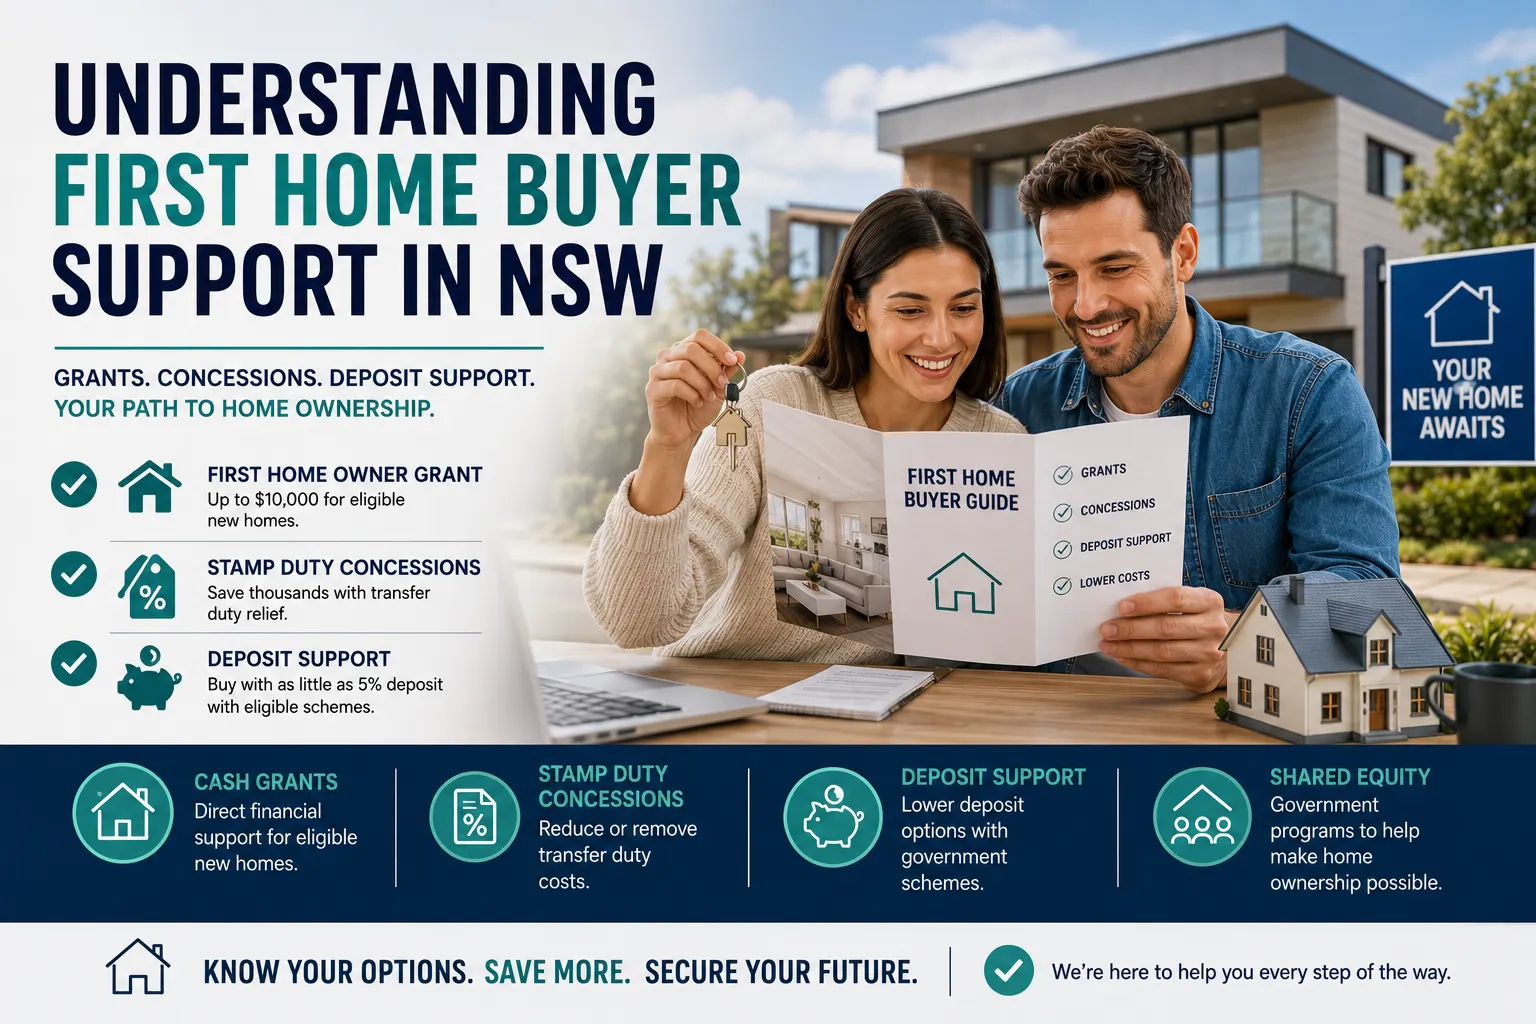
- Consider down payment assistance programs
Speaking of assistance, many of our first-time homebuyers are surprised to learn about available down payment help efficient capital will guide you to find which home loans are best for you in 2025. Over 2,000 down payment assistance programs exist nationwide, offering various forms of support including grants and forgivable home loans. These programs typically provide help with both down payment and closing costs.
For our professional clients, we often highlight employer assistance programs. Some companies, particularly in healthcare and education sectors, offer special mortgage affordability programs to help employees achieve homeownership. These can include forgivable home loans or matching programs that significantly reduce the saving burden.
Determining Your Ideal Down Payment Amount
When working with our Sydney clients, we’ve found that determining the ideal down payment amount is a highly personalized decision. Recent data shows that while repeat buyers typically put down 17% of the purchase price, first-time homebuyers average around 6%.
As home loan experts in Sydney, we recommend considering these key factors when determining your ideal down payment:
- Your current savings and emergency fund
- Monthly payment comfort level
- Long-term financial goals
- Local market conditions
- Available loan programs
Our experience shows that while a 20% down payment offers clear benefits, it’s not always the optimal choice. According to recent market data, the median down payment in many areas is around 13%, showing that many successful homebuyers put down less than the traditional 20%.
Finding Your Balance We’ve observed that once your down payment reaches 30-40%, you experience diminishing returns. This insight often surprises our Sydney clients who assume bigger is always better. For most conventional financing, we’ve found that a down payment of about one-third of the purchase price often represents an optimal balance.
Conclusion
Making the right down payment decision for your Sydney home loans purchase doesn’t need to be overwhelming. While a 20% down payment offers clear advantages, we’ve helped many clients achieve homeownership with various down payment amounts that better suited their situations.
Smart saving strategies, combined with available assistance programs, can make your down payment goals more achievable than you might think. Remember to maintain a healthy emergency fund alongside your down payment savings – this balance provides the financial security needed for successful homeownership.
Whether you’re ready to start house hunting or still building your savings, our team at Efficient Capital can help you determine the right down payment strategy for your circumstances. We’ll guide you through available loan options and help you make an informed decision that aligns with your long-term financial goals.