The Australian property dream is a cornerstone of our culture, but for many of us, the monthly mortgage notification on our phones has become a source of “rate-rise anxiety.” With the average new owner-occupier home loan in Australia sitting at $693,801, many households are feeling the pinch of monthly repayments that hover around $3,935.
While the headlines often scream about switching banks, the truth is that jumping ship isn’t always the first or best step. Refinancing comes with paperwork, potential discharge fees, and credit checks. Before you go through that hassle, there are several powerful strategies you can deploy right now with your current lender.
If you want to reduce your home loan cost, keep your lifestyle intact, and stop the bank from taking more than its fair share, this guide is for you.
1. The Power of the “Loyalty Tax” Negotiation
Many Australians are unknowingly paying a “loyalty tax.” This is the gap between what a bank offers new customers and what they charge its existing, loyal borrowers. According to the Reserve Bank of Australia, the average rate on outstanding owner-occupier loans is 5.51% p.a., while new loans are often dragged lower to 5.48% p.a. to entice new business.
You don’t have to leave your bank to get a better deal. A simple phone call to your lender’s retention department can often result in a rate reduction. Armed with the knowledge that average variable rates for owner-occupiers are approximately 5.85% p.a., you can ask your bank to match the market.
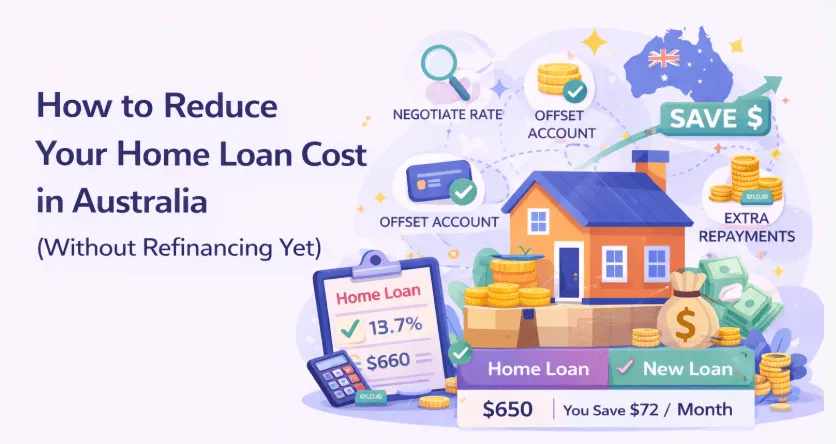
If you can secure even a small 0.25% reduction, the impact is significant. Data shows that for a loan between $600,000 and $1 million, a 0.25 percentage point difference can save you between $90 and $150 every single month. That is money back in your pocket without changing a single thing about your daily life. Home loan services of Efficient Capital can help you understand exactly what rates are currently competitive, so you have the upper hand in these negotiations.
2. Master the Offset Account
An offset account is perhaps the most underrated tool to reduce your home loan cost. It functions like a standard transaction account but is linked directly to your mortgage. The balance in this account is “offset” against your loan balance when interest is calculated.
For example, if you have a $600,000 loan and $50,000 in a 100% offset account, the bank only charges you interest on $550,000. Because interest is calculated daily, every dollar sitting in that account—even for a few days—is working to reduce mortgage costs.
To maximise this, have your salary paid directly into the offset account and use a credit card for daily expenses (paying it off in full before the interest-free period ends). This keeps your cash sitting against your loan for as long as possible, effectively lowering the home loan interest you accrue over the life of the loan.
3. Increase the Frequency, Not Just the Amount
Most Australians default to monthly repayments because it aligns with their bills. However, switching to fortnightly or weekly payments is a subtle but effective way to pay off a home loan faster.
There are 12 months in a year, but 26 fortnights. If you take your monthly repayment and simply halve it to pay fortnightly, you end up making the equivalent of 13 monthly payments a year. This “hidden” extra payment goes directly toward the principal, which in turn helps lower home loan repayments in the long run by reducing the total interest charged.
On a standard $600,000 loan, this simple administrative tweak can shave years off your mortgage and tens of thousands of dollars off your total interest bill.
4. Make Small, Consistent Extra Repayments
We often think we need a massive windfall to make a difference, but the math suggests otherwise. Even an extra $50 or $100 a month can have a compounding effect on your debt.
When you make an extra repayment, 100% of that money goes toward the principal. This reduces the base upon which your home loan interest is calculated, the very next day. If you’ve received a small tax return or a modest pay rise, diverting that cash into your mortgage is one of the most effective ways to reduce your home loan cost.
For an owner-occupier with a $600,000 loan, even small movements in the interest rate environment can shift your minimum requirements. By paying more than the minimum now, you build a “buffer” that protects you from future rate hikes.
5. Review Your Loan Features and Fees
Are you paying for “gold-plated” features you don’t use? Many “Package” home loans charge an annual fee (often between $300 and $400) in exchange for credit card fee waivers or slightly lower interest rates.
If your loan balance has decreased or you no longer use the bundled credit card, you might be better off on a “Basic” or “No Frills” loan. While the interest rate might look similar, removing the annual fee and streamlining your loan structure is a guaranteed way to reduce mortgage costs.
Check your statements:
- Are you paying a monthly service fee?
- Are you paying for an offset account you aren’t actually keeping money in?
- Is your rate significantly higher than the current average variable rate of 5.85% p.a.?
If the answer is yes, it’s time to ask your lender to switch your product internally.
6. Understand Your Local Market Context
The urgency to reduce your home loan cost often depends on where you live. Average monthly repayments vary wildly across Australia:
- NSW: $4,696
- Victoria: $3,667
- Queensland: $3,897
- Northern Territory: $2,729
If you live in a high-cost area like Sydney or Melbourne, your loan is likely larger, meaning every 0.10% of interest you save has a much larger dollar-value impact. Using government data from the Housing Loan Interest Rate dashboard can help you see how your current rate stacks up against others in your specific state.
Taking Control Today
You don’t have to wait for the RBA to cut rates to lower home loan repayments. By negotiating with your current lender, using an offset account effectively, and increasing your payment frequency, you can take control of your financial future today.
The goal is to reduce your home loan cost by attacking the interest from all angles. Whether it’s through a rate review or disciplined extra repayments, the small steps you take now will save you thousands of dollars over the next 20 to 30 years.
If you’re unsure if your current bank is giving you the best deal possible, or if you want to explore how to pay off your home loan faster, reach out to Efficient Capital Solutions. We specialise in looking at the fine print so you can focus on enjoying your home, rather than just paying for it.