Securing a home loan in Sydney‘s current market might seem daunting when you look at the numbers. The median dwelling price stands at $766,000, requiring monthly repayments of $3,833 with a standard 20% deposit and 6.4% interest rate.
However, several home loan options in Sydney exist specifically for low-income earners, even if you earn the minimum wage of $882.80 per week. In fact, many lenders now consider various income sources, including government payments, rental income, and pensions when evaluating loan applications. You’ll find home loan options in Sydney through government initiatives like the Home Guarantee Scheme, which allows eligible buyers to enter the property market with just a 2% deposit, without paying Lenders Mortgage Insurance.
Government Support Programs in Sydney
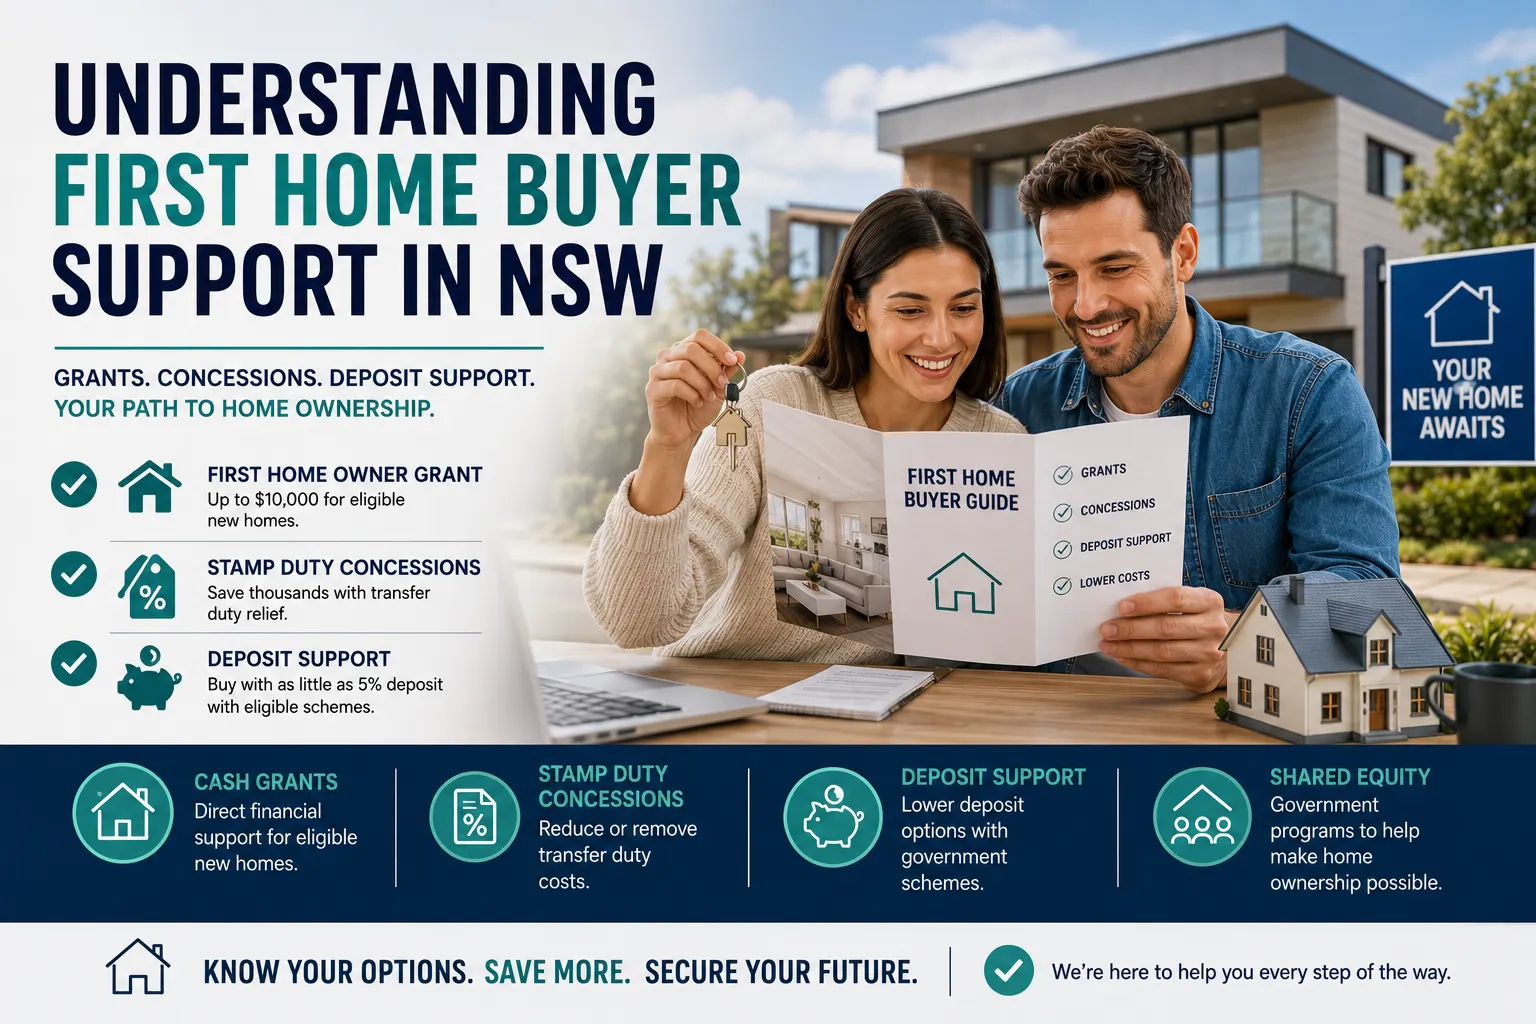
The NSW government offers substantial support to help low-income earners achieve homeownership. First-time buyers can receive a full exemption from transfer duty on properties valued up to $800,000. For homes valued between $800,000 and $1 million, a concessional rate applies.
The First Home Owner Grant provides $10,000 for buyers purchasing or building new homes valued under $600,000. Accordingly, this grant helps offset initial costs, although certain conditions must be met. For instance, you must:
-
Be at least 18 years old
-
Be an Australian citizen or permanent resident
-
Move into the property within 12 months
-
Live there continuously for at least 12 months
The Home Guarantee Scheme enables eligible buyers to enter the market with minimal deposits. Under this program, first-home buyers need only a 5% deposit, whereas single parents can qualify with just 2% through the Family Home Guarantee. Home loan options in Sydney under this scheme allow buyers to avoid Lenders Mortgage Insurance, as Housing Australia guarantees up to 15% of the loan value.
Income thresholds also apply across these programs. Generally, single applicants must earn no more than $125,000 annually, while couples can earn up to $200,000 combined. These limits ensure that home loan options in Sydney remain accessible to those who need financial support the most.
Finding the Right Lender
Choosing between traditional banks and alternative lenders marks a crucial decision in your home loan journey. The big four banks—ANZ, CommBank, NAB, and Westpac—currently hold approximately 75% of Australia’s owner-occupier home loans. Still, smaller lenders often present compelling advantages for low-income borrowers.
Smaller lenders typically offer more competitive interest rates and reduced fees due to their lower operational costs. These institutions demonstrate greater flexibility in lending criteria, making them an excellent choice if your credit rating needs improvement. Plus, their streamlined processes often result in faster loan approvals.
Traditional banks bring distinct benefits, including extensive branch networks and comprehensive financial services. Their established processes and substantial resources typically enable faster home loan approvals, sometimes within a week. Additionally, they operate under strict regulation by the Australian Prudential Regulatory Authority (APRA), offering enhanced security.
Most lenders treat applications from low-income earners on a case-by-case basis. A mortgage broker can help navigate home loan options in Sydney, connecting you with lenders more likely to consider your application.
Conclusion
Securing a home loan in Sydney certainly appears challenging, especially for low-income earners facing median house prices of $1.47 million. However, multiple pathways exist through government initiatives and flexible lending options that make homeownership achievable.
Traditional banks, non-bank lenders, and government support programs each offer unique advantages. The First Home Owner Grant provides $10,000 for new homes, while the Home Guarantee Scheme allows deposits as low as 2%. Additionally, stamp duty exemptions and concessions help reduce upfront costs significantly.
Efficient Capital understands these challenges and specializes in finding home loan options in Sydney for low-income borrowers. Our team analyzes your specific financial situation, matches you with appropriate lenders, and guides you through available government support programs. Take the first step toward homeownership today—schedule a consultation with our expert mortgage advisors who will create a personalized pathway to help you secure your dream home in Sydney.